What Is APF in Real Estate? A Buyer's Guide to Approved Project Finance
Visit almost any new launch in Gurgaon and the sales brochure will proudly list a row of bank logos with the words "APF approved". Sales teams use it as a badge of trust, and it often is one. But many buyers don't know what APF actually means, what the bank checked before giving it, and, just as importantly, what it doesn't promise. A clear understanding can help you get your home loan faster and avoid reading too much into a logo.
What Is the APF Full Form in Real Estate?
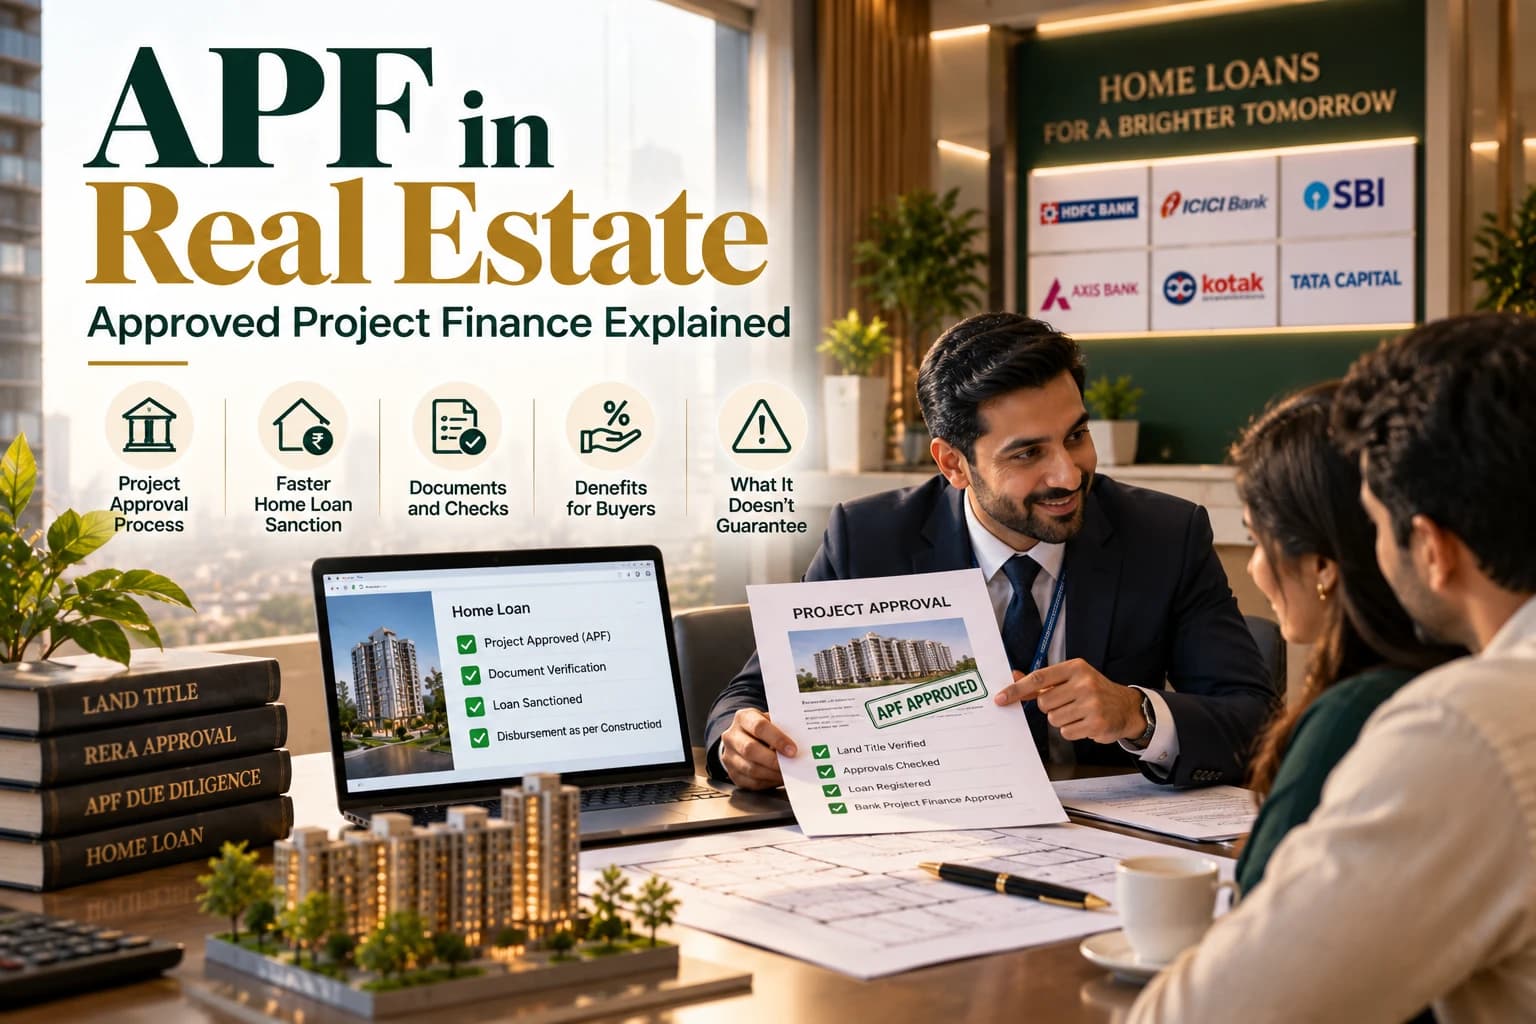
The APF full form is Approved Project Finance (sometimes written as Approved Project Financial). It means a bank or housing finance company has reviewed a real estate project and approved it for home loan funding.
Once a lender approves a project, it gives it a unique APF number, which it uses to identify the project across its branches. Buyers in that project can then get home loans with less paperwork on the project side, because the lender has already checked it.
In simple terms, the APF meaning is this: the bank has done its homework on the project, so it only needs to check you, the borrower.
How Does a Bank Approve a Project for APF?
Before issuing an APF number, the lender's legal and technical teams typically review:
- Land title and ownership, to confirm the developer has a clear, marketable title to the land
- Licences and approvals, such as the DTCP licence in Haryana, approved building plans and environmental clearances
- RERA registration of the project
- The developer's track record, including past deliveries, financial strength and experience
- Technical feasibility, including the construction plan, site condition and progress
- Encumbrances, to check whether the land or project is mortgaged elsewhere
The developer usually applies to several banks, which is why one project may be approved by many lenders, each with its own APF number. Banks typically approve projects by tower or phase, so one part of a project may be approved while another is still under review.
Benefits of Buying in an APF-Approved Project
- Faster home loan sanction, since the bank doesn't need to re-verify the project for each buyer
- Fewer documents on the property side, because legal and technical checks are already done
- An extra layer of scrutiny, as a bank's legal team has reviewed the land title and key approvals
- Easier disbursement in under-construction projects, with payments released in line with construction progress
- Access to tie-up offers, as some lenders run special rates, processing fee waivers or pre-approved loan offers for projects they've approved
- Wider choice of lenders, when several banks have approved the same project, letting you compare rates
Why Developers Want APF Approval
For developers, an APF approval is a sales tool as much as a financial one:
- It builds buyer confidence, especially for new or lesser-known developers
- It speeds up sales, since most buyers depend on home loans
- It makes subvention and special payment plans possible, which often need a lender tie-up
- It improves cash flow, because loan disbursements reach the developer faster
That's why you'll see bank logos on almost every brochure and site banner.
APF vs RERA vs OC: What APF Does Not Guarantee
APF is useful, but it's not a stamp of safety. It's important to know where it fits.
APF is a lender's internal approval to fund a project. It shows the bank found the project's paperwork acceptable at the time of review.
RERA registration is a legal requirement. It's what allows the developer to market and sell the project, and it gives you statutory protection and a forum for complaints.
OC (Occupation Certificate) confirms the finished building follows approved plans and is fit to live in.
An APF approval does not guarantee timely possession, construction quality or the developer's future financial health. Banks also state that approving a project is only for funding purposes. Your individual loan is still decided on your income, credit score and the lender's own due diligence. Projects with bank approvals have still faced delays, so treat APF as one positive signal, not the final word.
Can You Get a Home Loan for a Project Without APF?
Yes. A project without an APF number from your chosen bank isn't automatically a bad project. It just means that bank hasn't reviewed it yet, or the developer hasn't applied.
In that case, the lender will carry out its own legal and technical verification of the property as part of your loan application. Expect more documents, a longer processing time and possibly a property valuation visit. Resale properties, independent builder floors and smaller projects are often financed this way.
That said, if no major bank has approved a large under-construction project, it's worth asking why before you commit.
How to Check the APF Status of a Project
Don't rely only on logos in a brochure. To verify:
- Ask the developer for the list of approving banks and the APF numbers, in writing
- Check the lender's website, as several banks publish lists of approved projects with project names, approved towers and APF numbers
- Call or visit the bank's home loan desk and give the project name and tower
- Confirm the tower and phase you're buying in is covered, not just the project name
- Cross-check with RERA, making sure the project's registration matches what the bank approved
Things to Check Before Relying on APF
- The APF number and lender name, confirmed directly with the bank
- That your specific tower or phase is covered by the approval
- The project's RERA registration number and its completion date
- The developer's track record on past deliveries
- The terms of any subvention or tie-up scheme, including who pays the pre-EMI interest and what happens if possession is delayed
- Your own loan eligibility, since APF doesn't guarantee approval of your loan
Final Thoughts
An APF approval is a genuinely useful signal. It means a lender's legal and technical teams have looked at the project and are willing to fund it, which makes your home loan faster and smoother. But it's a bank's comfort, not a buyer's guarantee. Use APF as a shortcut to your loan, and then do the rest of your homework: check RERA, study the developer's record and read the payment terms before you sign.